
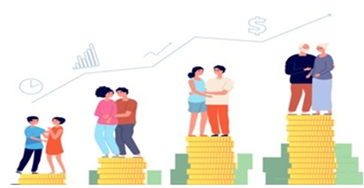
You should have a retirement plan in advance, so that when you retire from work, you continue to maintain the same life-style without worrying about expenses and inflation. A retirement plan helps you to pursue your post-retirement dreams and to secure your future.
Some tips for Your Retirement Planning:
- Saving early for retirement gives money more time to grow and compound. This ensures availability of a large lump sum on your retirement.
- Make sure you save enough to cover unplanned expenses and emergencies. Ensure that you have adequate insurance policies to cover unforeseen events and medical emergencies to secure your family and loved ones.
- It is desirable to diversify your investments across different asset class so that if one asset class does not perform, you can get returns from other asset class. Put it simply, don't keep all your eggs in one basket.
- Choose your plan keeping in mind your retirement goals and lifestyle. You may contact a regulated financial advisor to guide you through the retirement planning process who will help you find the best retirement plans for you.
Build Your Financial Future Independently
Being unmarried can be an ideal stage to establish strong financial habits and work towards your personal goals. *Financial planning for unmarried individuals* focuses on managing income, building savings and preparing for important future milestones.
Key Areas of Financial Planning
- Emergency fund planning
- Investment and savings planning
- Home and property planning
- Career and income growth goals
- Insurance and financial protection
- Retirement planning
- Tax and long-term financial planning
- Planning for future marriage or family responsibilities
Start Planning Early
With fewer financial responsibilities, you may have greater flexibility to focus on long-term goals. Starting early can provide more time to build savings and investments according to your financial goals, time horizon and risk profile.
Plan Your Financial Future
Understand your goals, organise your finances and take informed steps towards building a financially prepared future.
Plan Together. Build Your Future Together.
Marriage brings shared financial responsibilities, new priorities and long-term goals. *Financial planning for married couples* helps organise household finances and create a structured approach towards achieving individual and family goals.
Key Areas of Financial Planning
- Joint financial goal planning
- Household budget and cash-flow management
- Emergency fund planning
- Home purchase planning
- Child education planning
- Insurance and financial protection
- Investment and wealth planning
- Retirement planning
- Tax and estate-related considerations
Plan for Every Stage of Family Life
As your family and financial responsibilities evolve, your financial plan may need to be reviewed periodically. A structured approach can help you assess your goals, savings, investments, protection needs and future financial requirements.
Build Your Family's Financial Future
Understand your shared financial goals and explore an investment approach based on your objectives, time horizon and risk profile.
Start Your Family Financial Plan
The cost of delaying investments is the potential wealth you lose by postponing your savings. Every year you delay investing reduces the time available for your money to benefit from the power of compounding. As a result, you may need to save significantly more later in life to achieve the same financial goals.
Quantifying the Cost of a 10-Year Delay
To understand the impact of delaying investments, consider two hypothetical investors who both plan to retire at the age of 60. Both invest INR 500 per month and earn an assumed 8% average annual return, compounded monthly. The only difference is that one investor starts investing 10 years earlier.
| Metric | Investor A (Starts at Age 30) | Investor B (Starts at Age 40) |
|---|---|---|
| Monthly Contribution | INR 500 | INR 500 |
| Investing Timeline | 30 years | 20 years |
| Total Out-of-Pocket Invested | INR 180,000 | INR 120,000 |
| Final Portfolio Value at Age 60 | INR 750,147 | INR 296,473 |
The Total Cost of Delay Investor B finishes with INR 453,674 less wealth, despite only saving INR 60,000 less out-of-pocket.
Identifying Why Delaying Costs You Wealth
- Compounding Curve Suppression: Compounding growth is exponential, meaning the biggest gains occur during the final years of investing.
- Higher Required Principal: Waiting forces you to invest significantly larger monthly amounts to achieve the same financial goal as an early investor.
- Inflation Purchasing Power Erosion: Cash kept idle gradually loses purchasing power as the cost of goods and services rises over time.
- Missed Market Cycles: Delaying investments may cause you to miss opportunities to invest during market downturns when valuations are lower.
Executing a Strategy to Reclaim Lost Time
If you are starting your investment journey later than planned, consider the following steps to reduce the financial gap:
- Calculate Your Target Deficit: Determine your financial goal and use an investment calculator to estimate the monthly amount required.
- Maximize Tax-Advantaged Catch-Up Contributions: Make use of applicable catch-up contribution limits available to eligible investors.
- Automate Your Monthly Investments: Set up automatic investment transfers to maintain consistency and avoid emotional decision-making.
- Optimize Asset Allocation: Ensure your portfolio maintains an appropriate balance between equity and debt investments based on your goals and risk profile.
Download Xl here
To track and hit your retirement goals effectively, you should use a mix of specialized digital goal trackers, benchmark milestones based on your salary, and a structured math framework to ensure your savings outpace inflation.
Here is an end-to-end framework to build, track, and optimize your retirement goal tracker.
2. Measure Progress via Age-Based Savings Benchmarks
A quick way to check if your goal tracking is on target without deep math is using annual income multipliers. According to standard fidelity and financial guidelines:
| Current Age | Target Savings Milestone |
|---|---|
| Age 30 | 1X of your current annual salary |
| Age 40 | 3X of your current annual salary |
| Age 50 | 5X of your current annual salary |
| Age 60 | 7X of your current annual salary |
Download Xl here
Retirement Planning for Seniors
Plan Your Retirement. Protect Your Independence.
Retirement is a new phase of life where financial stability, regular income, healthcare and unexpected expenses become important. A well-planned retirement strategy can help you manage your savings and investments while preparing for your future financial needs.
The focus should be on *financial stability, appropriate risk management and long-term sustainability*, rather than simply seeking higher returns.
Financial Planning for Your Retirement Years
Your financial priorities can change during retirement. Planning should consider:
- Regular retirement income
- Essential household expenses
- Healthcare and emergency needs
- Inflation and rising living costs
- Existing savings and investments
- Insurance and financial protection
- Tax considerations
- Nomination and succession planning
Regular reviews can help ensure your financial arrangements continue to match your changing needs.
Key Areas of Retirement Planning
1. Regular Income Planning
Assess your pension, investments and other income sources to determine whether they can support your regular expenses throughout retirement.
2. Emergency Fund
Maintain an appropriate reserve for unexpected medical, household and other financial requirements.
3. Healthcare Planning
Review your health insurance and keep a provision for medical expenses that may not be covered.
4. Inflation Planning
Consider the impact of rising costs on your future purchasing power and retirement income requirements.
5. Risk Management
Investment decisions should consider your financial goals, risk tolerance, investment horizon and liquidity requirements.
6. Asset Allocation
Diversifying investments across suitable asset classes can help manage risk while aligning investments with your objectives.
7. Withdrawal Planning
Plan withdrawals carefully to meet your income needs while considering the sustainability of your retirement corpus.
8. Nomination & Succession
Keep nominations and important financial records updated. Consider appropriate legal guidance for succession and estate planning.
9. Tax Planning
Understand the applicable tax treatment of your income and investments and seek professional tax guidance where required.
Common Retirement Mistakes to Avoid
- Depending on a single source of income
- Taking unnecessary investment risk
- Ignoring inflation
- Making unplanned withdrawals
- Keeping financial records outdated
- Selecting investments based only on past performance
Review Your Retirement Plan
Periodically review your:
Income . Expenses . Healthcare . Investments . Insurance . Nominations . Financial Goals
Your retirement plan should evolve as your financial circumstances and priorities change.
Important Investor Information
This content is for *general investor education and awareness purposes only* and should not be considered personalised investment, tax or legal advice.